
Asset-Backed
The equipment itself serves as collateral. No additional assets required.
Applying will not impact your credit score.
Get up to 90% of your equipment’s value to purchase the machinery, vehicles, and tools your business needs. Fixed payments, same-day decisions, funded in as little as 24 hours.
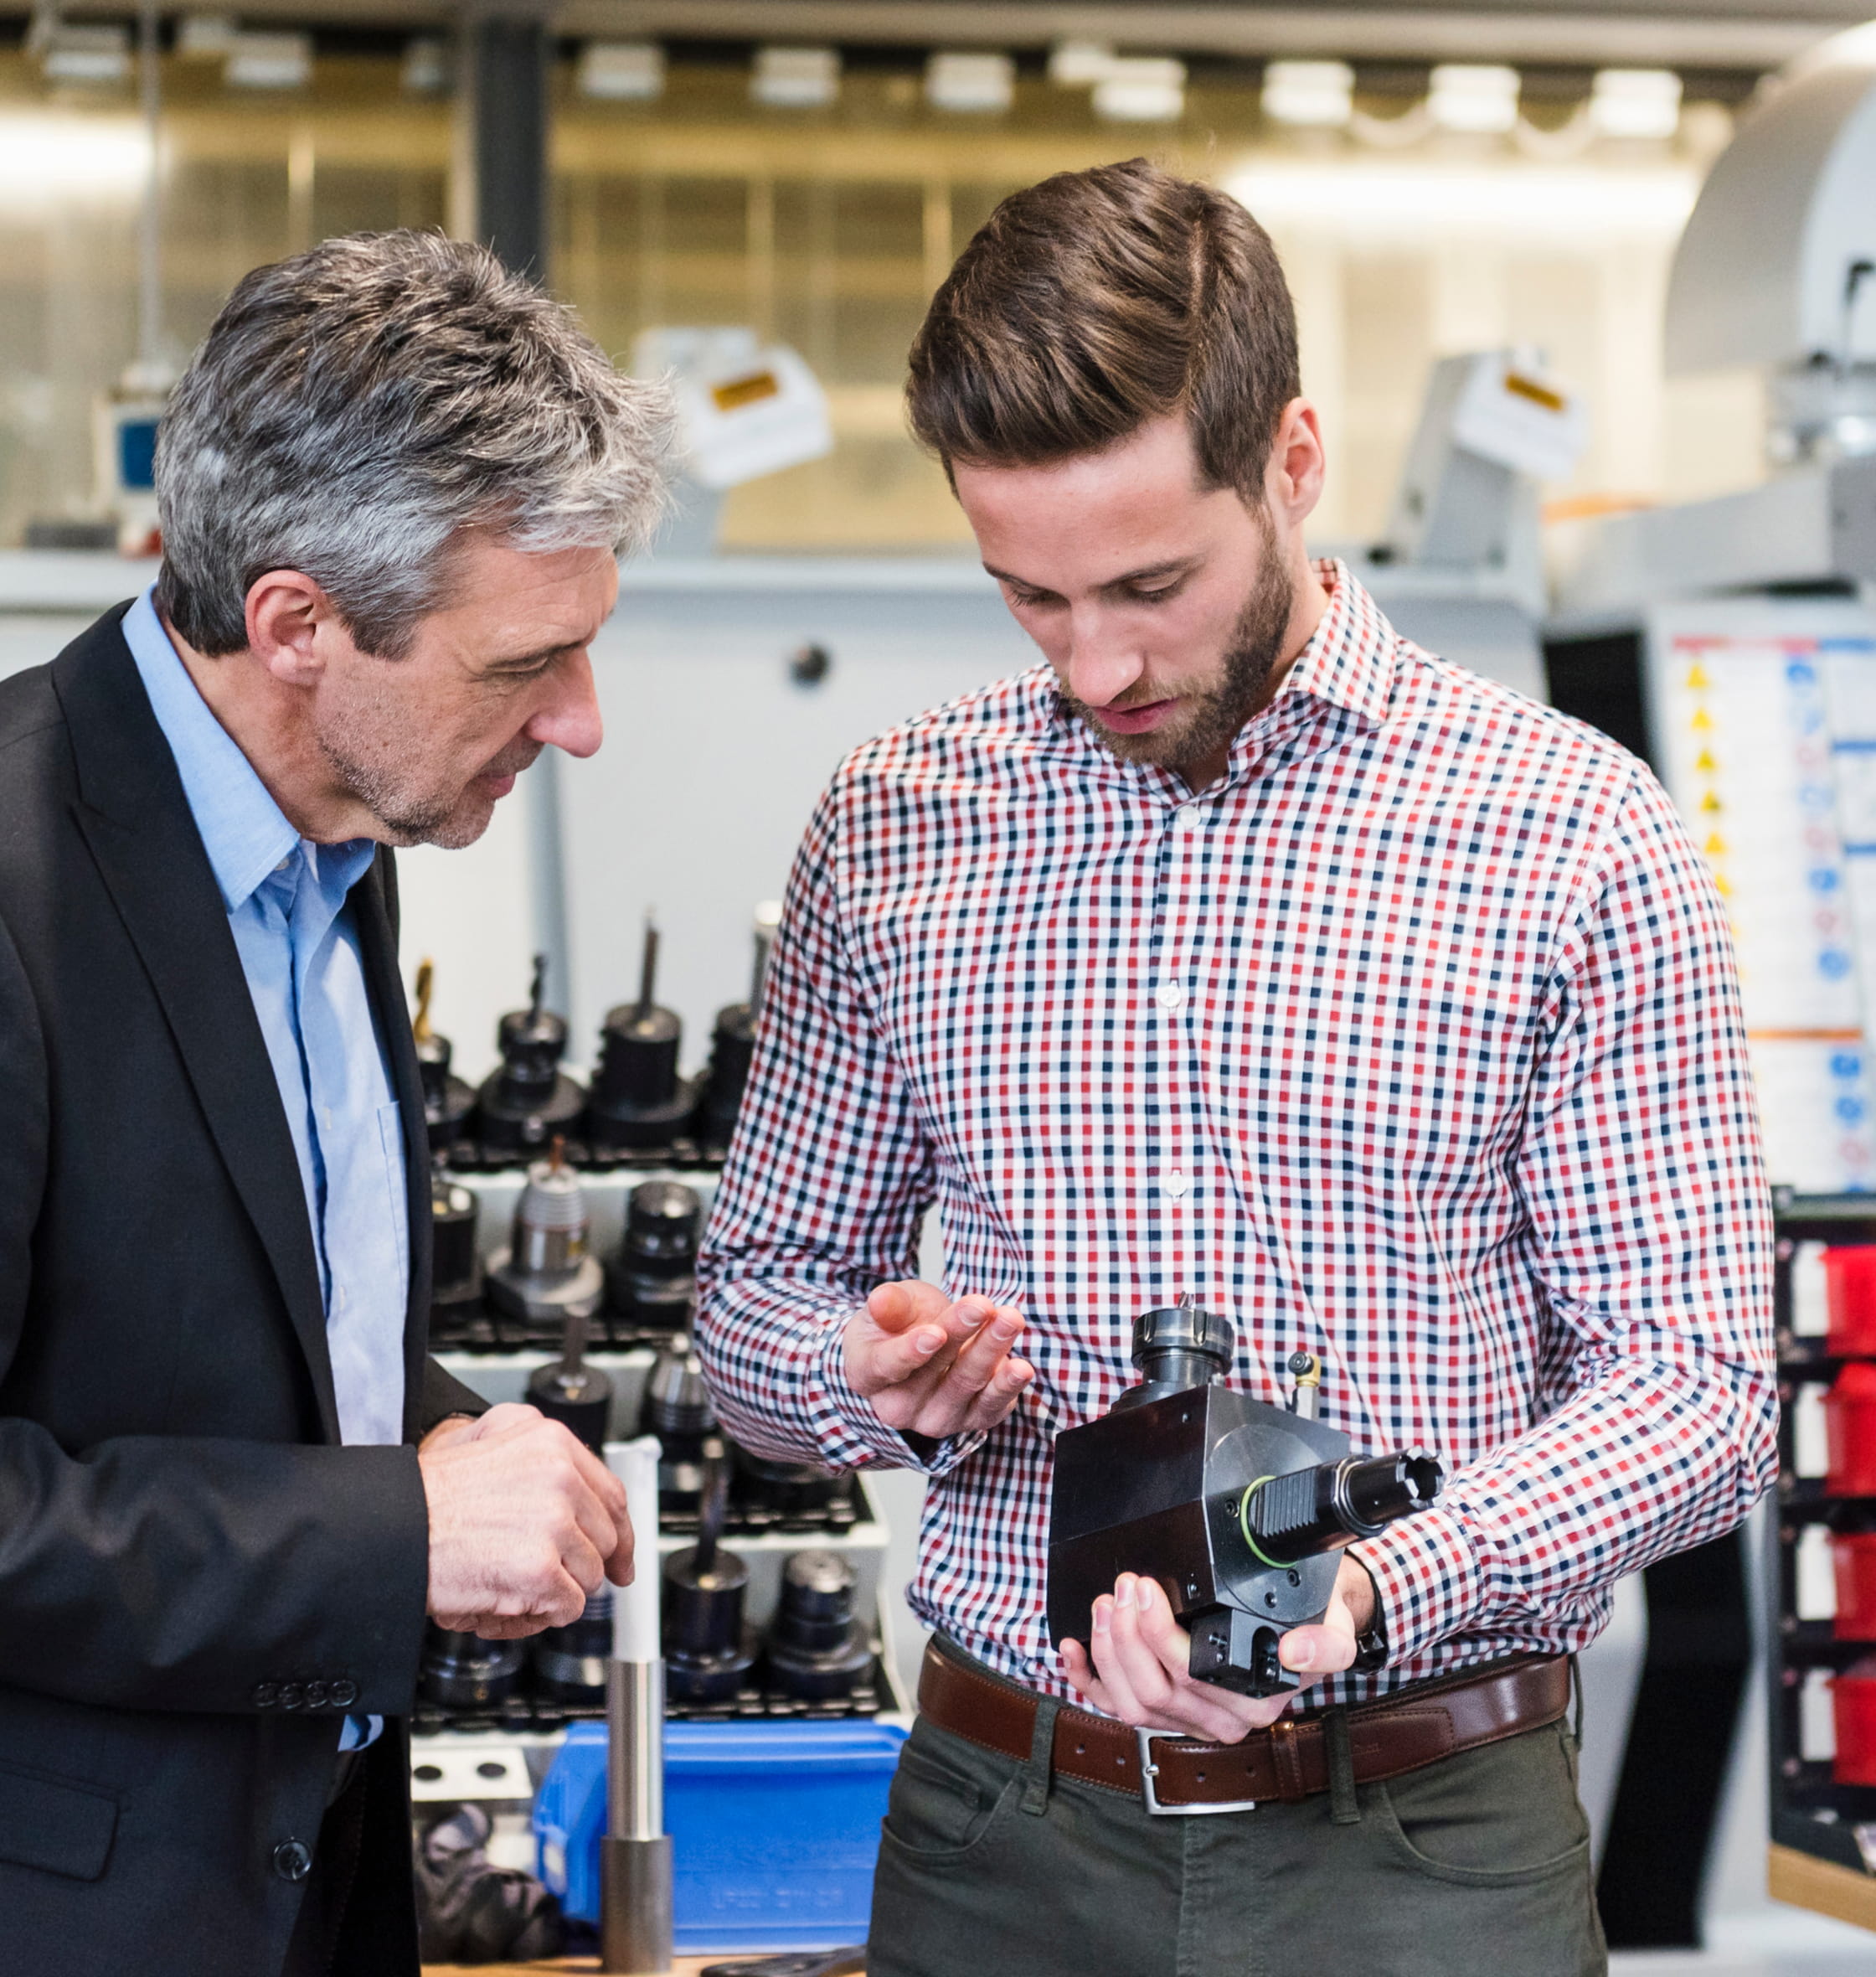
Equipment financing is financing structured for the purchase of physical business assets: machinery, vehicles, medical devices, industrial tools, technology hardware. The equipment you purchase serves as collateral, so you are not required to pledge other business or personal assets to qualify. SBG Funding advances up to 90% of the purchase price upfront; you take ownership immediately and repay on a fixed schedule over a term matched to the equipment’s useful life. In practice: a CNC machine that accounts for a significant share of your output is failing, and repair costs are approaching the value of the machine itself. A replacement runs $85,000. Pulling that from your operating account would wipe out the working capital you use for raw materials and payroll between orders. Financed instead, the machine is purchased, your working capital stays intact, and the fixed payment fits your cost structure for the next two to five years.
SBG Funding matches repayment terms to the asset, from 2 to 5 years. Approval is based on the equipment’s value, your revenue history, and your business profile. Unlike a business term loan or business line of credit, the asset itself secures the financing. Most applications are reviewed the same business day, with funds available in as little as 24 hours.
Bank equipment financing exists. A bank underwrites against two years of filed financials and a 680 credit score, often with a $50,000 minimum. Banks aren’t built to turn around a financing decision in the window between a machine failing and a production deadline, which means the businesses under the most operational pressure are the ones a bank is slowest to serve. SBG Funding performs no hard credit pull, so applying does not affect your credit score. We evaluate more than 50 factors, including the equipment’s value, your revenue history and deposit patterns, rather than relying primarily on credit score.
Asset-Backed
The equipment itself serves as collateral. No additional assets required.
Up to 90% LTV
Available financing amount based on your equipment and business profile.
2–5 Years
Fixed repayment schedule matched to the useful life of your equipment.
Compare your options
See how SBG Funding stacks up against other financing sources.
Traditional Bank
Other Online Lenders
Won’t affect your credit score.
If your business runs on physical assets, equipment financing is one of the most efficient ways to acquire them.
Equipment financing is the right tool when you need a physical asset and want to preserve your working capital.
You’re Purchasing or Replacing a Major Asset
A new piece of machinery, a replacement vehicle, a medical device, or a technology system. Any equipment purchase with a defined cost and a multi-year useful life is a strong candidate. The asset secures the financing, which means you are not drawing down your operating capital or pledging other business assets. The equipment generates the revenue that repays the financing.
You’re Expanding Capacity Without Touching Working Capital
Adding equipment to increase throughput, take on larger contracts, or serve more clients requires capital, but it should not come at the expense of the cash you need to run current operations. Equipment financing keeps your line of credit and operating account intact while the new asset comes online and starts generating return.
You Want Predictable Payments Tied to the Asset
Equipment financing structures repayment around the useful life of the asset, typically 2 to 5 years, with fixed weekly or monthly payments. You know exactly what the equipment costs per month for the life of the financing, which aligns your financing cost directly with the revenue the equipment produces.
SBG Funding evaluates 50+ factors, including the value of the equipment being financed, your revenue history, and your time in business. Businesses with strong cash flow may qualify for equipment financing even with an imperfect credit score.
annual revenue
min. FICO score
months in business
bank statements
Complete our quick online application in about 5 minutes. Basic information about your business and financing needs — no lengthy paperwork to get started.
Our team reviews your application and presents financing options matched to your business profile. We look at revenue, deposit history, and time in business — not just your credit score.
Once approved and documents are signed, funds can be in your business bank account in as little as 24 hours.
$3B+
Funded since 2017
via Trustpilot
I just wrapped up with Andrew Wolff of SBG Funding and he made it very easy to navigate the process! He answered all my questions and was on top of the process every step on the way. I recommend SBG Funding and really think Andrew Wolff is the BEST!
“Cole at SBG Funding went the extra mile to get me the funding I needed for my business to take on the growth it needed. It would’ve been really challenging to take on the larger projects without hiring new help and getting the proper tools and equipment.”
5×
Inc. 5000 honoree
via Better Business Bureau
He was very attentive, communicated with me every step of the way, and acted as the liaison between me and the funding companies. I also appreciated that he took the time to find a funding option that made sense for my business without putting me into something that would cost me more than necessary.
4.9
Trustpilot rating
A
BBB rating
via Trustpilot
Phone was blowing up with offers but so glad I didn’t ignore THIS call! Despite every other company promising same day funding, Brian O’Grady explained why SBG’s reputation helped secure my lending decision, my lending options and what to realistically expect. And it turned out to be even smoother and less painful as expected!
85%
Approval rate
via Better Business Bureau
Had a great experience with SBG Funding. Andrew Wolff was able to secure a positive outcome for my company and it was done quickly. He walked me through the procedure and made everything clear and easy to understand. No beating around the bush, no lengthy back-and-forth correspondence. Straight to the point. I recommend their service absolutely!
4.9
Google rating
via Better Business Bureau
She was the kindest, most thoughtful broker I’ve ever spoken to and I’m so grateful for her help. Would recommend her to anyone!
SBG Funding requires a minimum FICO score of 500. Because the equipment itself serves as collateral, equipment financing is often more accessible than unsecured business financing for businesses with imperfect credit. Strong revenue, consistent deposits, and a sound equipment purchase can all support your application even if your credit score is below 620.
Helpful: 0 / Not helpful: 0
After approval and document submission, funds can be available in as little as 24 hours. The online application takes about 5 minutes, and most applicants receive a decision the same business day.
Helpful: 0 / Not helpful: 0
The equipment you are purchasing serves as collateral for the financing, which is standard practice across the equipment financing industry. You are not required to pledge real estate, other business assets, or personal property. The equipment secures the financing; a personal guarantee may also be required.
Helpful: 0 / Not helpful: 0
SBG Funding’s equipment financing covers a wide range of business assets, including manufacturing and production machinery, commercial vehicles and fleets, medical and diagnostic equipment, construction and heavy equipment, restaurant and food service equipment, technology and point-of-sale systems, and most other physical business assets with a defined purchase price and a useful life measured in years. Both new and used equipment are eligible.
Helpful: 0 / Not helpful: 0
SBG Funding offers equipment financing terms from 2 to 5 years, with fixed weekly or monthly payment options. Your specific term is based on the type of equipment, its purchase price, and your business profile. Longer terms are typically available for larger, longer-lived assets like heavy machinery and commercial vehicles.
Helpful: 0 / Not helpful: 0
Yes. SBG Funding’s equipment financing is available for both new and used equipment purchases. The age and condition of the equipment may affect the funding amount and term, and used equipment with a shorter remaining useful life may qualify for a shorter repayment term. Contact your funding specialist to discuss your specific purchase.
Helpful: 0 / Not helpful: 0
Yes. With equipment financing, you own the equipment outright at the end of the financing term. The asset is yours from day one, and the financing is secured by it. With equipment leasing, you make payments for the right to use the equipment but do not own it at the end of the term, though some leases include a buyout option. Equipment financing is generally preferred when you plan to use the asset long-term and want to build equity in it.
Helpful: 1 / Not helpful: 0
Both products provide a lump sum upfront with fixed repayment, but there are two key differences. First, equipment financing uses the asset as collateral, which means no additional collateral is required and approval criteria are often more flexible. Second, equipment financing terms of 2 to 5 years are typically structured around the useful life of the equipment, while a business term loan runs 6 to 48 months and is more flexible in purpose.
Helpful: 1 / Not helpful: 0
Yes. SBG Funding works with businesses across a wide range of industries, including healthcare, construction, manufacturing, automotive services, food service, beauty and wellness, and veterinary practices. Equipment financing is available for industry-specific assets as long as they have a defined purchase price and a useful life that supports the repayment term.
Helpful: 0 / Not helpful: 1
To get started, you need your 4 most recent business bank statements and information about the equipment you are purchasing, including type, price, and vendor if available. For larger financing amounts, we may also request business tax returns or additional financial documentation. No lengthy business plan or audited financials are required to begin the process.
Helpful: 0 / Not helpful: 0
Whether you’re replacing aging machinery, adding a vehicle to your fleet, upgrading your medical or diagnostic equipment, or expanding production capacity, SBG Funding’s equipment financing puts the asset in your hands. Fixed payments, same-day decisions, and no requirement to pledge anything beyond the equipment itself. Apply online in minutes. No hard credit pull, no obligation.